Is Your Family Financially Prepared for a Medical Emergency? | Pathway 316
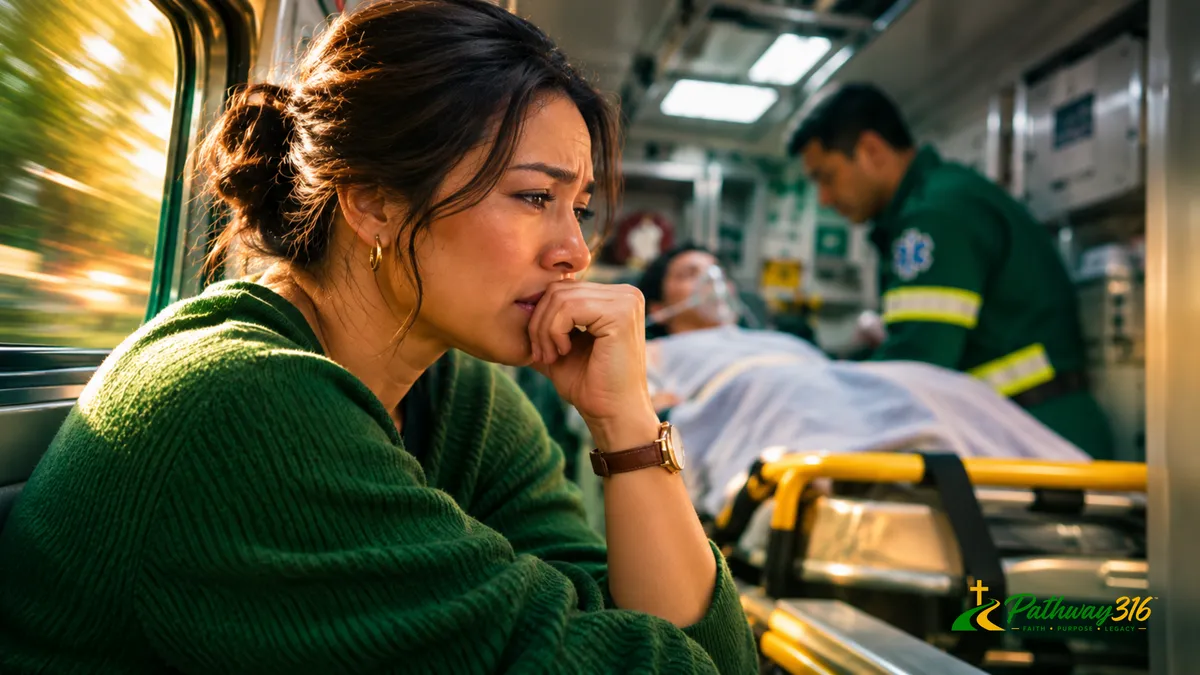
A medical emergency can begin with a phone vibrating on the kitchen counter. Someone has been taken to the hospital. Plans disappear. A spouse is calling relatives, a parent is finding childcare, and somebody is trying to remember which insurance card is current.
Then money enters the room. The deductible comes up. Someone starts counting missed workdays. Prescriptions, parking, childcare, and bills keep moving. If the patient cannot speak for themselves, the family may also be figuring out who can make decisions.
A medical emergency can create a financial chain reaction across coverage, income, savings, family responsibilities, and debt.
A little preparation ahead of time can leave fewer money decisions competing for attention when someone you love needs care.
Know What Your Health Plan May Still Leave You Owing
Health insurance can cover part of a major medical bill. Deductibles, copayments, coinsurance, and other plan costs may remain.
An out-of-pocket maximum generally applies to covered in-network care. Premiums, non-covered services, out-of-network care, and charges above the allowed amount can fall outside it. (Source: HealthCare.gov)
That maximum gives a household a ceiling for covered in-network cost-sharing, though other emergency costs remain. Childcare, parking, travel, missed work, premiums, and non-covered care can still affect the budget.
Those plan details belong beside the money needed to keep everyday life running.
Under EMTALA, most hospital emergency departments must provide an appropriate screening and, when an emergency medical condition exists, stabilizing treatment or an appropriate transfer regardless of insurance status or ability to pay. (Source: Centers for Medicare & Medicaid Services)
The Household Budget May Change Before the Medical Bills Arrive
The first financial hit may be lost income. Federal FMLA can provide eligible workers of covered employers with up to 12 workweeks of job-protected leave for qualifying medical situations, but federal FMLA leave is generally unpaid. (Source: U.S. Department of Labor)
Housing, utilities, groceries, transportation, childcare, and other essentials may still be due while someone works fewer hours or stops working.
Estimate how long the household could keep paying those expenses if one paycheck became smaller or stopped for several weeks.
The financial pressure during a medical emergency is often a timing problem. Income can fall quickly while costs rise.
Emergency savings and health-related accounts may help. HSA distributions can generally be tax-free when used for qualified medical expenses, while a health FSA can reimburse qualified medical expenses under its own rules.
Before an emergency, know which funds are available, where the account information is, and which expenses may qualify. (Source: Internal Revenue Service)
Decide Who Can Step In Before Someone Has To
A health care proxy, sometimes named through a durable power of attorney for health care, can authorize someone to make medical decisions if you cannot communicate. An advance directive can also record care preferences.
Requirements vary by state, so families should use the forms and signing rules that apply where they live. (Source: National Institute on Aging)
During a hospitalization, the document that matters is the one someone can actually find.
A signed proxy stored in an old folder, an inaccessible laptop, or a place nobody else knows about may leave relatives searching as decisions move quickly.
Families benefit from knowing where the documents are kept, who has copies, and who has been named to step in.
When the Bill Comes, Give It a Second Look
If insurance was used, CMS recommends comparing the provider’s bill with the Explanation of Benefits, checking that the “your share” amount matches, requesting a detailed bill when needed, and looking for charges that do not match the care received or appear more than once. (Source: Centers for Medicare & Medicaid Services)
Errors, duplicate charges, and unresolved insurance issues can change what the household actually owes.
Verify the bill before deciding how the balance will affect savings, monthly cash flow, or debt.
A medical emergency can reveal financial weak spots that ordinary weeks never test. Insurance may suddenly need to be understood in detail. Savings may have to cover missed wages and unexpected expenses. Important documents may exist without being easy to find.
Preparation reduces the number of financial questions a family has to solve while its attention belongs with someone they love.
Look at the Whole Financial Picture
Pathway 316 is built around that wider view of financial life.
The app brings health care, insurance, budgeting and savings, debt management, estate planning, retirement planning, tax planning, and financial wellness into a faith-centered education framework.
Looking at those areas together can show where more preparation or professional guidance may be needed.
Pathway 316 offers faith-centered financial education, tools, and guidance across multiple areas of financial life. Questions requiring individualized legal, tax, investment, or other licensed professional advice should be reviewed with an appropriately qualified professional.
Visit Pathway316.com to see how the parts of your financial life connect and where more preparation may be needed before an unexpected medical event puts them to the test.
Download the Pathway 316 app and start building a clearer faith-based financial future, all in one place.